Shares fell 22.64% in 90 days, despite a positive three-year return. Expansion could lift revenue, but debt and Las Vegas exposure weigh on the valuation case.
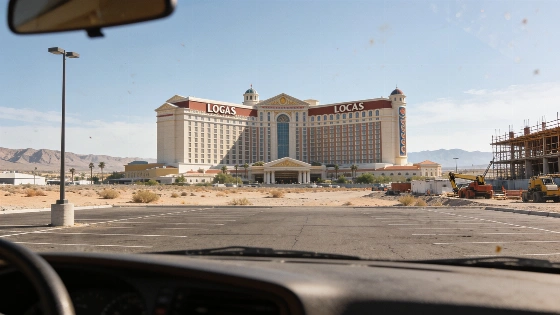
Construction is progressing on the northern expansion at Durango, one of the projects investors are counting on to drive future growth.
Red Rock Resorts closed at US$49.51 after falling 22.64% over 90 days. A widely followed investor narrative puts the shares 33% below fair value, but the company’s debt and reliance on Las Vegas locals demand complicate that case.
The longer-term return tells a different part of the story. Red Rock’s three-year total shareholder return remains positive at 31.63%, even as the recent decline puts the valuation under pressure.
For the quarter ended June 30, Red Rock Resorts reported revenue of $510.26 million and net income of $39.12 million, compared with $526.27 million and $56.4 million a year earlier, respectively.
The growth case behind the valuation
Durango North is planned to add more than 275,000 square feet of casino and entertainment space. Nevada Globe reports that the northern expansion includes about 400 additional gaming machines and tables. Plans also call for a 36-lane bowling alley. Premium cinemas are planned, along with a two-story, 29,000-square-foot Moonshine Flats venue.
Food-hall turnover is also part of the changes at Durango’s Eat Your Heart Out. That shift comes as the expansion moves forward.
Nevada Globe reports that Uncle Paulie’s, Yu-Or-Mi Sushi and Vesta Coffee are closing at Durango’s Eat Your Heart Out food hall as the expansion moves forward. Station Casinos said it expected to announce the replacement restaurant operators in the following weeks; the new brands had not yet been identified in the report.
Red Rock’s other growth project is the fully financed North Fork tribal casino, scheduled to open in early Q4 2026. Both developments could add revenue and adjusted EBITDA, but that potential does not remove the risks tied to the existing business.
Recent Red Rock Resorts documents are listed in the SEC database. The available search results do not provide their contents, so they do not independently confirm updated debt or EBITDA figures. They also do not confirm North Fork’s launch timing.
Debt and local-market exposure
Net debt stands at about US$3.5 billion, and leverage is above 4x. Heavy capital spending adds pressure as Red Rock pursues expansion with a significant debt load. Its business is concentrated in Las Vegas, leaving earnings exposed to shifts in local demand.
That concentration hangs over the growth plan. The figures provided do not establish that expansion will offset the company’s debt burden or local-market risk.
What the share-price gap says
The most popular investor narrative puts fair value at about US$73.39, well above the US$49.51 close, and calls the stock 33% undervalued. That is a market view, not a promised return. Shares fell 11.43% over 30 days and 22.64% over 90 days, despite the positive three-year return.
Investing.com’s market review also described the shares as down about 23% over three months. It characterized demand in the Las Vegas locals casino market as stable. Deutsche Bank maintained a Buy rating and a US$73 price target.